Discover Pandipedia
A growing directory of useful answers selected by the Pandi community. Search the collection or browse the latest discoveries.
2292 entries available
CISA’s ICS exposure-control checklist: cut reachability first
Internet-reachable industrial control systems (ICS) are exposed. CISA advises reducing reachability first, then using firewalls and separating ICS/OT from business networks. Check affected software or firmware versions and follow vendor mitigation or support guidance. For legacy or unpatchable assets, remove Internet access where possible. If remote access is required, use an updated secure VPN; its security depends on the connected devices.

Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Should KEV outrank CVSS in vulnerability triage?. Compare severity-only triage with exploitation-led triage using KEV, EPSS, vendor remediation status, and asset exposure as the core decision inputs. Include a table separating confirmed exploitation, probability of exploitation, remediation action, and when to remove unpatchable assets from networks.
Should KEV outrank CVSS in vulnerability triage?
Yes. The attached CISA and EPSS sources support an exploitation-led triage model: confirmed exploitation in CISA KEV should outrank severity-only CVSS scoring, while EPSS is used as a probability signal when active exploitation is not already evidenced.[1][2][3]
The practical takeaway is that CVSS should inform context, but not drive priority by itself when there is evidence of exploitation, clear mitigation guidance, or high asset exposure.[4][5]
How the triage inputs differ
CISA KEV is explicitly built around vulnerabilities with evidence of active exploitation, and CISA says those items should be prioritized for rapid remediation.[6] EPSS, by contrast, estimates the likelihood of exploitation in the next 30 days and is most useful when you do not already have evidence of active exploitation.[7]
| Decision input | What it means | How it should affect triage |
|---|---|---|
| Confirmed exploitation[8] | Evidence that the vulnerability is being exploited in the wild | Top priority, ahead of severity-only CVSS |
| Probability of exploitation[9] | EPSS estimate of likely exploitation in the next 30 days | Use when exploitation is not already confirmed; raise priority as probability increases |
| Vendor remediation status[10][11] | Whether there is clear mitigation or vendor guidance | Faster action when a clear remediation path exists; if not, escalate containment or removal |
| Asset exposure[12][13] | Whether the vulnerable asset is publicly exposed or internet-facing | Increase urgency, especially for publicly exposed assets |
Action guide: confirmed exploitation vs probability vs exposure
| Situation | Recommended action | When to remove or isolate from network |
|---|---|---|
| Confirmed exploitation | Remediate immediately using required CISA/vendor guidance[14][15] | If patching or mitigation cannot be completed in time, remove the asset from the network or isolate it[16][17][18] |
| High EPSS but no confirmed exploitation | Prioritize ahead of lower-probability issues, especially if the asset is exposed[19][20] | Use removal or isolation when the asset cannot be updated fast enough and exposure is material[21][22] |
| Vendor has clear mitigation guidance | Apply mitigations, vendor instructions, and CISA-required actions[23][24][25] | Consider isolation as a temporary control if mitigation is incomplete[26][27] |
| Unpatchable asset | Decommission, remove the vulnerable product, segment, isolate, or otherwise discontinue use[28][29][30][31] | Remove from the network or isolate it when no timely update or mitigation is available[32][33] |
Bottom line
For triage, KEV should outrank CVSS because it captures known exploitation, which is the strongest signal in the provided sources.[34][35] Use EPSS to rank unconfirmed cases by likelihood, then adjust for vendor remediation status and asset exposure. If an asset cannot be patched or mitigated quickly, CISA guidance supports removal from the network or isolation rather than leaving it exposed.[36][37][38][39]
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
RSE Collection fractional collectibles: what investors should notice
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Five Wix 20-F risk themes that keep coming back
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Why Traceable Data Beats Bigger Data
Transcript
Three very different systems point to the same lesson. In the software quality patent, quality is assessed by tracing requirements through a Scenario Branch Diagram, then a scenario diagram, then a method flow diagram, with metrics built around scenario logic, business rules, state transitions, and interface complexity. In PATSTAT Global, the patent database is organized around family, application, and publication, with explicit linkage rules and governed tables so the data can support statistical research, innovation monitoring, and policy decisions. And in OpenCorporates, entity verification starts from legal entity data, uses an API, supports continuous monitoring, and records provenance so teams can audit where information came from and when it was collected. The shared pattern is not simply more data, but traceable objects inside governed data models. That is what turns raw records into reliable decisions for analysts, compliance teams, and operators.
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
How does Vinci Compass turn assets under management into distributable earnings?. Break down the model into fee related earnings, performance related earnings, investment related earnings, distributable earnings, fundraising dependence, liquidity needs, and major market risks. Use tables to separate revenue drivers from risk exposures and to show why the company presents resilience while still acknowledging cyclical earnings.
Vinci Compass: how AUM turns into distributable earnings
The filings describe a layered model in which assets under management feed recurring fees first, then more variable performance and investment economics, and finally a dividend-oriented distributable earnings measure.[1][2][3]
In short, the business can look resilient because a large part of earnings comes from a recurring fee base, but results are still cyclical because performance fees, investment gains, fundraising, and market conditions can swing with the cycle.[4][5][6]
Revenue drivers: AUM to earnings bridge
| Driver | What it is in the filings | How it behaves |
|---|---|---|
| Fee Related Earnings (FRE) | Recurring management and advisory fees, described as the baseline operating or durable fee base.[7][8] | Most resilient layer because it is tied to ordinary operating revenue from ongoing AUM.[9][10] |
| Performance Related Earnings (PRE) | Realized performance fees tied to fund performance above hurdle rates.[11][12] | Cyclical and timing-dependent because fees are only realized when funds outperform.[13][14] |
| Investment Related Earnings (IRE) | GP commitments or proprietary capital invested alongside clients, including GP capital gains.[15][16] | Market-linked and realization-dependent, so more variable than FRE.[17][18] |
| Distributable Earnings | The board’s dividend metric, built from profit for the year after removing unrealized performance fees and unrealized investment income, plus specified adjustments.[19][20] | Designed for distributability rather than as a pure operating measure.[21][22] |
The model is therefore: AUM supports fee income, fee income becomes FRE, successful fund performance creates PRE, co-invested or GP capital creates IRE, and the company then converts accounting profit into Distributable Earnings by stripping out unrealized items and making agreed adjustments.[23][24][25][26]
Risk exposures: what can disrupt the earnings bridge
| Risk exposure | What the filings say | Why it matters for earnings |
|---|---|---|
| Fundraising dependence | Growth depends heavily on successor fundraising because funds have finite lives, and weaker performance or shifting investor preferences can make replacement capital harder to raise.[27][28] | Weak fundraising can slow AUM growth and therefore reduce future fee base expansion.[29][30] |
| Liquidity needs | The company says it must fund growth, capital commitments, contingent liabilities, operating expenses, and litigation contingencies, and may need to sell assets or raise debt or equity on unfavorable terms if liquid assets are insufficient.[31][32] | Liquidity pressure can force unfavorable financing or asset sales and constrain capital deployment.[33][34] |
| Major market risks | The filings highlight difficult market and economic conditions, including interest rates, inflation, exchange rates, political uncertainty, trade tension, wars, currency controls, and broader Latin American macro, political, and currency risks.[35][36][37] | These risks can affect AUM values, fee generation, realizations, and investment returns.[38][39][40] |
| Other operating risks | The filings also flag AUM declines, difficult exits, reduced financing availability, portfolio company distress, illiquid or junior investment losses, and technology change including AI.[41][42][43] | These can weaken both the recurring and cyclical earnings layers at the same time.[44][45] |
Why the company can look resilient, yet still cyclical
The resilience comes from the FRE layer: a recurring management and advisory fee base that the filings present as the durable operating core.[46][47][48]
The cyclical side comes from PRE and IRE, both of which depend on market performance, realizations, and the timing of fund outcomes. That means distributable earnings can remain supported by fees while still moving around with fundraising, exits, and market conditions.[49][50][51][52][53]
Bottom line: Vinci Compass presents a model with a recurring fee anchor, but the filings clearly show that distributable earnings are not immune to cycles in fundraising, liquidity, and Latin American market risk.[54][55][56][57][58][59]
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Choose the Right Policy Evaluation Method
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
How to verify company claims in EDGAR without getting fooled by the exhibit type
An EDGAR filing date isn’t necessarily a report’s effective date. The Pretium EX-99.1 shows how a new filing can contain an older report, so its claims may be technically old even when the filing is recent. The exhibit can identify its label, report, authors and project, and show it was prepared for S-K 229.1300 compliance. But it alone does not prove legal title, completed transactions, reserves, or that projections will come true.
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
The Hidden Tradeoffs in Intergovernmental Grants
Transcript
Intergovernmental grants can do real good, but the OECD warns they also carry hidden side effects. One common risk is the fly paper effect, where recipients increase spending by more than they would after an equal rise in local income. Grants can also crowd out own source taxes, because local governments may find it easier to rely on transfers than to raise taxes themselves. Another concern is procyclicality, when grants move in step with local economic swings and end up reinforcing spending booms and busts. The note also points to accountability problems, since large or poorly designed grants can weaken the link between citizens and elected local officials. The bigger lesson is simple: do not expect one grant instrument to solve every problem. Grant design works best when it is matched to one specific objective, because trying to do everything at once can reduce transparency, blur the results, and create inefficiency.
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
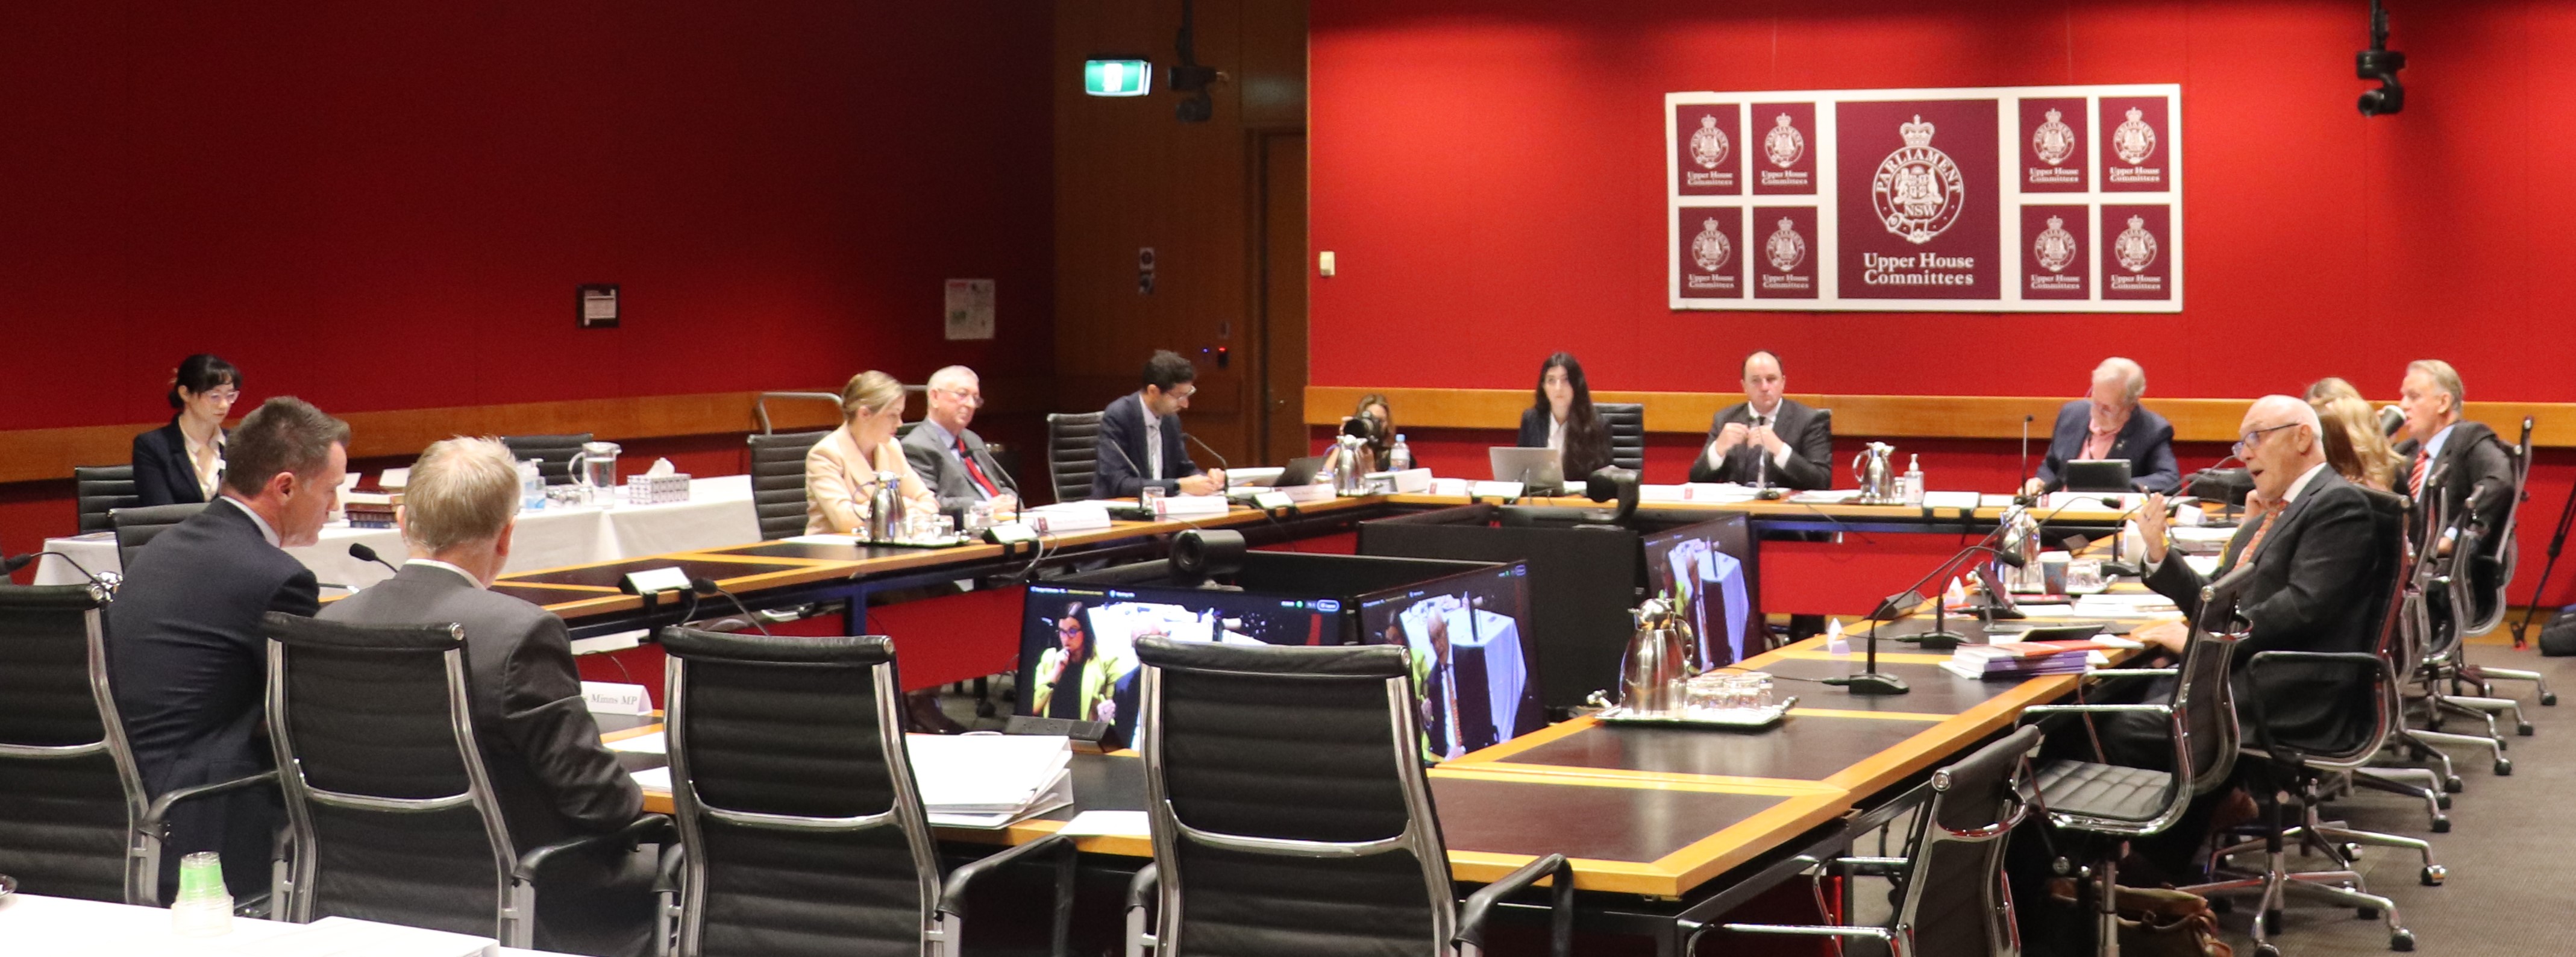
How parliaments can make evidence-based lawmaking routine
Evidence-based lawmaking requires a full loop: evidence in drafting, timely access for parliamentary scrutiny, and review after laws pass. In the Western Balkans, preparation evidence, including RIAs, does not always reach parliament, while committee scrutiny faces weak documentation, tight timetables and poor co-ordination. Scrutiny can draw on research services, experts and civil society. Yet post-legislative review remains sporadic, leaving little fact-based feedback on whether laws worked.

Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).