Discover Pandipedia
A growing directory of useful answers selected by the Pandi community. Search the collection or browse the latest discoveries.
2292 entries available
One Climate Process, Two Reporting Regimes
Transcript
Can ISSB and ESRS climate reporting come from one integrated process? The sources say yes, realistically, for most of the overlap. The interoperability guidance is designed to reduce complexity, fragmentation, and duplication, and it shows that substantially all ISSB climate disclosures are also included in ESRS. But the fit is not perfect. ESRS uses double materiality, while ISSB focuses on investor decision-useful information, so ESRS can require extra climate disclosures beyond the ISSB baseline. For teams, that means one shared core for data collection, governance, controls, metrics, targets, and risk management, with ESRS-specific branches where the broader scope goes further. In short, one shared framework is practical, but it should be built for divergence, not for identical output.
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
FY 2023 climate disclosure: uptake rose, completeness lagged
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
IFRS S2, TPT, and ESRS E1: how climate transition plans connect to finance. Compare IFRS S2, TPT, and ESRS E1 across the treatment of transition plan existence, investor relevance, 1.5 degree alignment, CapEx and OpEx, funding, and governance. Include a framework table and a practical implications section for sustainability, finance, and investor relations teams.
IFRS S2, TPT, and ESRS E1: how transition plans connect to finance
This brief compares how IFRS S2, the IFRS/TPT transition plan disclosure framework, and ESRS E1 treat climate transition plans as a finance-facing disclosure topic. The key differences are whether a plan must exist, how strongly the disclosures are aimed at investors, how 1.5°C alignment is treated, and how explicitly the frameworks connect transition plans to CapEx, OpEx, funding, and governance.[1][2]
The broad pattern is that IFRS S2 is primarily a disclosure standard for entities that already have transition plans, TPT provides a more detailed investor-oriented disclosure framework, and ESRS E1 is the most explicit about mandatory transition-plan disclosure and its connection to technical and financial planning.[3][4][5]
Framework comparison table
| Topic | IFRS S2 | TPT framework | ESRS E1 |
|---|---|---|---|
| Does a transition plan have to exist? | An entity does not have to have or publish a transition plan, but if it has one, it discloses it or cross-references it.[6] | Discloses "any climate-related transition plan" an entity has, rather than requiring every company to have one.[7] | Transition-plan disclosure is mandatory under ESRS E1-1 for climate change mitigation, although undertakings without a full plan may disclose a mitigation action plan instead.[8] |
| Investor relevance | Disclosures are intended to be useful to primary users such as investors, lenders, and other creditors because they support risk pricing and capital allocation.[9] | Designed as investor-relevant disclosure that improves information for pricing risk and making capital allocation decisions.[10] | Presented as a strategic summary for users of the management report, helping them assess ambition, robustness, and the link between technical and financial planning.[11] |
| 1.5°C alignment | No blanket requirement that every plan be 1.5°C aligned; jurisdictions may add such information if it remains clearly identifiable.[12] | Plans should respond to the latest scientific findings and the Paris Agreement goal of limiting warming to 1.5°C above pre-industrial levels.[13] | Plans should explain compatibility with limiting warming to 1.5°C and benchmark targets to a 1.5°C reference pathway, though the guidance also says the compatibility issue is not addressed in this document.[14][15] |
| CapEx and OpEx | Climate strategy disclosures may include current and anticipated changes in resource allocation, including capital expenditure and R&D spending.[16] | Requires disclosure of investment and disposal plans, expected effects on financial position, performance and cash flows, including capital expenditure and asset retirements.[17] | Requires disclosure of investment and funding supporting implementation, including capital and operating expenditures, and links this to taxonomy-aligned CapEx and CapEx plans.[18][19] |
| Funding | Disclosures may cover funding the implementation of a strategic goal.[20] | Requires disclosure of planned sources of funding.[21] | Undertakings must explain and quantify the investments and funding supporting implementation, and disclose the financial resources allocated to the plan.[22] |
| Governance | Governance is an explicit disclosure area, including board or oversight responsibility, management accountability, incentives and remuneration, skills and competencies, and annual reporting on progress against quantified and timebound metrics and targets.[23][24] | Includes board or oversight responsibility, management accountability, incentives and remuneration, skills and competencies, and annual reporting against quantified and timebound metrics and targets.[25][26] | The plan should be overseen by the highest levels of governance and disclose approval by the administrative, management, and supervisory bodies, together with integration into strategy and business model.[27] |
Practical implications for sustainability, finance, and investor relations teams
- Sustainability teams: treat the transition plan as the single source of truth for mitigation strategy, targets, governance, and the resource pathway behind the plan. ESRS E1 is the most explicit about linking technical actions to financial planning, while TPT and IFRS S2 help structure what should be disclosed to capital-market audiences.[28][29][30]
- Finance teams: make sure the plan can be translated into budget, CapEx, OpEx, and funding language. ESRS E1 expects quantified investments and funding, and the TPT/IFRS materials connect transition planning to financial position, performance, cash flows, and capital allocation decisions.[31][32][33]
- Investor relations teams: prepare a consistent narrative on whether the company has a plan, how credible it is, whether it is aligned to a 1.5°C pathway, and how progress will be tracked. IFRS S2 is more permissive on plan existence, so IR teams should avoid implying that every issuer must already have a formal plan unless required by jurisdiction.[34][35][36]
- Cross-functional priority: ensure governance approvals, ownership, and annual progress reporting are aligned across sustainability, finance, and board reporting, because all three frameworks emphasize decision-useful, investor-facing disclosure rather than standalone narrative commentary.[37][38][39]
Bottom line
If you want the shortest synthesis: IFRS S2 says disclose a transition plan if you have one; TPT gives a detailed investor-focused template for what that disclosure should contain; and ESRS E1 turns transition planning into a mandatory sustainability reporting topic with especially strong links to governance, funding, and CapEx/OpEx planning.[40][41][42]
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Turn NIST AI RMF into an operating rhythm, not a binder
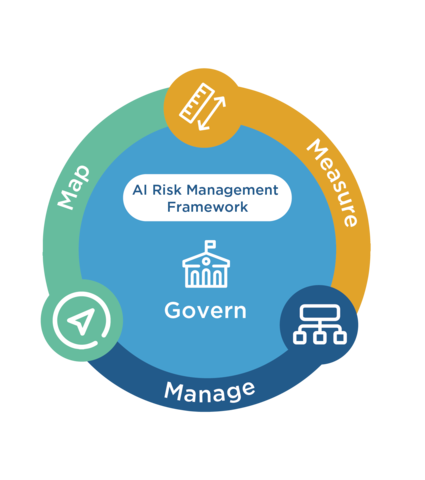
NIST’s AI Risk Management Framework (AI RMF) is an ongoing cycle, Govern, Map, Measure and Manage, shaped by the use case and risk profile, not a policy shelf. Govern establishes accountability, roles and oversight. Map defines purpose, context, stakeholders, scope and risk tolerance, helping prioritize high-risk uses. Measure and Manage test significant risks, choose responses such as mitigation, acceptance or decommissioning, and continue monitoring and change management after deployment.

Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Comparative GLP-1 and GIP Weight-Loss Evidence Quiz
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
What do Article 50 AI transparency duties mean for generative AI compliance?. Synthesize the EU AI Act transparency duties for AI interactions, synthetic content, deepfakes, and public-interest text, then compare them with the Commission guidance and NIST provenance recommendations. Include a table separating binding legal obligations from voluntary implementation supports and a section on why watermarking, metadata, and detection should be treated as layered controls rather than guarantees.
Article 50 transparency duties for generative AI compliance
Article 50 of the EU AI Act creates binding transparency duties for AI interactions, synthetic content, deepfakes, and certain public-interest text. The Commission’s draft guidance is meant to help providers and deployers implement those duties, but it is still draft guidance, not the legal obligation itself.[1][2]
In practice, this means compliance is not just about “putting a label on AI output.” The legal duty is to inform users and viewers, while the implementation layer can include marking, labelling, provenance signals, and detection support.[3][4][5]
Binding legal obligations vs voluntary implementation supports
| Category | What it requires or supports | Status |
|---|---|---|
| AI interactions | People must be informed when they are interacting with an AI system so they know they are dealing with a machine and can make an informed decision[6]. | Binding legal obligation under Article 50 |
| Synthetic content | AI-generated content must be identifiable; the Commission draft guidance says generative AI systems should use machine-readable marks so synthetic content can be detected as AI-generated or manipulated[7][8]. | Binding duty, with draft guidance on implementation |
| Deepfakes | Deepfakes must be clearly and visibly labelled, and deployers must also inform people when they are exposed to deep fakes[9][10]. | Binding legal obligation under Article 50 |
| Public-interest text | Text published with the purpose of informing the public on matters of public interest must also be clearly and visibly labelled[11]. | Binding legal obligation under Article 50 |
| Commission draft guidance | Explains implementation of Article 50 and notes the rules become applicable on 2 August 2026[12]. | Voluntary implementation support, not itself binding |
| Code of Practice on Transparency of AI-Generated Content | A voluntary tool to support compliance with Article 50; the Commission and AI Board said it is an adequate voluntary tool to demonstrate compliance[13]. | Voluntary implementation support |
| Code measures | Provides an EU-wide practical framework for labeling and detection of AI-generated content, deepfakes, and certain text publications[14]. | Voluntary implementation support |
| NIST provenance recommendations | Digital content transparency tools are building blocks, not comprehensive solutions, and often need normative, educational, regulatory, and market-based measures alongside technical controls[15]. | Voluntary implementation support and cautionary guidance |
The practical compliance split is simple: Article 50 tells you what must be disclosed, while the Commission draft guidance, the Code of Practice, and NIST help explain how to implement and operationalize that disclosure.[16][17][18]
Why watermarking, metadata, and detection are layered controls, not guarantees
The sources support a layered-controls view. Watermarking, metadata, and detection can all help with provenance and transparency, but none of them is reliable enough to stand alone as a guarantee that content will remain identifiable or that manipulation will always be caught.[19][20][21]
- Watermarking is fragile. NIST says covert and overt watermarks can often be removed, many schemes are vulnerable to scrubbing or spoofing, and text watermarking is especially hard to make robust[22].
- Metadata is not proof of truth. Embedded metadata can be copied, edited, or stripped, and signed metadata only proves that a signer attested to the data, not that the data itself is accurate[23].
- Detection is adversarial and incomplete. Automated and human-assisted detectors are in a constant cat-and-mouse game with generators, and they can struggle with post-processing, paraphrasing, short text, and cross-generator or open-set cases[24].
- Human-facing disclosure still matters. NIST notes that machine-readable provenance is not enough on its own; the information has to be presented to humans in a usable way[25].
So for generative AI compliance, the right posture is to combine: visible user disclosures, machine-readable marks, metadata where useful, and detection where feasible. That stack improves resilience, but it should never be treated as a guarantee of perfect provenance or perfect enforcement.[26][27][28]
Bottom line
For Article 50, compliance is about making AI involvement visible and understandable to people. The Commission draft guidance and Code of Practice provide helpful implementation paths, but the most defensible generative AI compliance strategy is layered: legal disclosure first, then technical marking, metadata, and detection as supporting controls, with NIST’s limitations in mind.[29][30][31][32]
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Is 80% adherence evidence-based? The review says not as a universal rule
An 80% medication-adherence cutoff originated as an empirical definition in early antihypertensive care: taking at least 80% was treated as sufficient. The review could neither confirm nor reject its validity, and says it was questioned as a general standard. The needed level may depend on disease, medication and patient characteristics. Studies measured adherence differently, so their rates could not be quantitatively compared or standardized.

Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Why stopping treatment changes the story on semaglutide versus tirzepatide
Transcript
When comparing semaglutide and tirzepatide for weight loss, it matters whether we are looking at trial efficacy or real-world use. Trials test ideal dosing and steady treatment, but in practice many patients stop early, stay on treatment inconsistently, or use lower doses than the trials studied. That means head-to-head results can look better in highly adherent patients than they do in everyday care. Tolerability also matters, because gastrointestinal side effects are a common reason people stop these medicines. And the weight loss itself may not last after treatment ends. The evidence says weight regain can happen after stopping semaglutide or tirzepatide, so comparative results should be read as on-treatment effects, not proof of durable weight loss once therapy is discontinued.
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
ATT&CK mapping decisions for detection engineering
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).
Comparing semaglutide and tirzepatide for weight loss. Synthesize the comparative evidence in sections covering study designs, populations, total body weight loss outcomes, safety and tolerability, heterogeneity, and head-to-head limitations. Include a compact table distinguishing what is strongly supported from what remains uncertain.
Comparing semaglutide and tirzepatide for weight loss
Across the attached evidence, both semaglutide and tirzepatide are among the most effective anti-obesity medications, with tirzepatide generally showing greater weight-loss effects in indirect comparisons. However, the overall comparison is driven mainly by network meta-analysis rather than extensive direct head-to-head trials.[1][2]
The key question is not whether both drugs work, but how much better tirzepatide appears to be, in whom that estimate is most reliable, and how much uncertainty remains because the evidence base is uneven across trial designs and populations.[3][4]
Study designs and populations
One source is a systematic review and network meta-analysis of 56 randomized controlled trials including 60,307 adults with obesity; nearly all trials were placebo-controlled, with only two multi-comparison studies. It also drew on related trials in conditions such as heart failure, prediabetes, metabolic dysfunction-associated steatotic liver disease, obstructive sleep apnea, and knee osteoarthritis.[5][6]
The other source is a network meta-analysis of 28 randomized controlled trials involving 34,367 participants, focused on the maximum approved doses of tirzepatide 15 mg and semaglutide 2.4 mg in people with overweight or obesity, with or without type 2 diabetes.[7]
Taken together, the evidence base is broad enough to compare class effects and rank therapies, but it is still dominated by placebo-controlled trials and indirect comparisons rather than many direct active-comparator studies.[8][9]
Total body weight loss outcomes
The strongest common finding is that both drugs produce clinically large total body weight loss. In the broader network meta-analysis, semaglutide and tirzepatide were the only treatments reaching at least 10% weight loss at 52 weeks, and tirzepatide was the only drug associated with at least 25% loss.[10][11]
In the semaglutide-versus-tirzepatide comparison, all assessed outcomes favored tirzepatide over semaglutide and placebo, including percentage body weight and body weight in kilograms, although the excerpted evidence does not provide exact effect sizes.[12]
The most defensible synthesis is that semaglutide is highly effective, but tirzepatide appears to deliver the greater average weight reduction in the currently available comparative evidence.[13][14]
Safety and tolerability
The broader obesity meta-analysis reports no significant increase in serious adverse events for obesity medicines overall, including semaglutide and tirzepatide, versus placebo, and discontinuation was similar to placebo overall.[15]
The tirzepatide-focused analysis describes adverse events as predominantly gastrointestinal, usually mild to moderate, with few serious events reported.[16]
So, the comparative safety signal is reassuring, but tolerability remains a practical issue because gastrointestinal effects are common for both agents.[17][18]
Heterogeneity and limitations of head-to-head inference
Heterogeneity is present and matters. In the broader review, the primary endpoint showed no inconsistency, but the 52-week analysis did show inconsistency, and baseline BMI, age, and comorbidity burden may have influenced treatment estimates.[19][20]
The tirzepatide-versus-semaglutide network analysis also notes heterogeneity assessment with Q, tau-squared, and I-squared, and suggests racial or ethnic background and comorbidity severity as possible contributors.[21]
The main limitation is that direct semaglutide-versus-tirzepatide evidence is scarce. One review notes that its active-controlled comparisons were liraglutide versus orlistat and semaglutide versus liraglutide, meaning tirzepatide was evaluated indirectly; it also highlights limited data for BMI below 30 kg/m², BMI at or above 40 kg/m², older adults, adolescents, and outcomes beyond two years.[22][23][24]
The other review similarly says the comparison depends largely on indirect evidence across studies with similar methods but different patient profiles, most follow-up is relatively short, and the only cited direct head-to-head study is SURMOUNT-5.[25][26]
What is strongly supported vs what remains uncertain
| Area | Strongly supported | Still uncertain |
|---|---|---|
| Comparative efficacy | Tirzepatide generally ranks above semaglutide for weight loss in indirect network evidence.[27][28] | Exact magnitude of advantage across all subgroups, because the accessible evidence is mostly indirect and not uniformly quantified.[29][30] |
| Weight-loss magnitude | Both drugs achieve large weight loss; semaglutide and tirzepatide were the only agents reaching at least 10% at 52 weeks, and tirzepatide was the only one linked to at least 25% loss in one review.[31][32] | How much of the apparent superiority is due to population mix, trial duration, and dosing differences.[33][34][35] |
| Safety | No clear excess of serious adverse events versus placebo overall; gastrointestinal events are the main tolerability issue.[36][37] | Whether one drug is clearly better tolerated than the other in direct comparative practice.[38][39] |
| Evidence base | The comparison is supported by large randomized-trial networks.[40][41] | Direct head-to-head evidence, longer-term follow-up, and data in underrepresented groups.[42][43][44][45] |
Bottom line
The attached evidence supports a practical conclusion: both semaglutide and tirzepatide are highly effective for weight loss, but tirzepatide appears to produce greater average total body weight loss in the available comparative literature, with broadly reassuring safety. The confidence in that ranking is limited by indirect evidence, heterogeneous study populations, and few direct head-to-head trials.[46][47][48][49]
Let's look at alternatives:
- Modify the query.
- Start a new thread.
- Remove sources (if manually added).