Découvrir Pandipedia
Un répertoire grandissant de réponses utiles sélectionnées par la communauté Pandi. Cherchez dans la collection ou parcourez les dernières découvertes.
2290 entrées disponibles
UNESCO media and information literacy policy resources
UNESCO media and information literacy policy resources
This curated set prioritizes UNESCO’s national policy and strategy guidance, with assessment tools and a policy-context brief to help educators and policymakers plan and evaluate media and information literacy initiatives.
Core national policy and strategy guidance
Start with UNESCO’s main strategy guide and its catalog record: these are the most direct resources for shaping a national media and information literacy approach.

Assessment and evidence for planning
These resources address assessing country readiness and competencies, helping connect national planning with evidence and evaluation.
Policy landscape and context
This issue brief provides context on media and information literacy policies and education, complementing the practical strategy guidance.
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
Financing longer lives: pensions, care and retirement technology
Financing longer lives: pensions, care and retirement technology
Longer lifespans mean retirement savings may need to support more years of income and a greater chance of needing ongoing care. This overview examines how pension reforms and public care programs respond, what long-term-care insurance can cover, and where digital tools may help people make retirement decisions.
The evidence points to a mixed-financing approach: public pension and care systems provide a foundation, private insurance may fill some care-cost gaps, and projections can help people compare retirement-income choices. But product terms vary, and the available research does not identify specific consumer retirement-planning platforms or establish that fintech tools solve the underlying affordability and longevity risks.
Policy and public programs: strengthening the foundation
Pension reform can improve the resources available in retirement, while long-term-care programs organize and finance services for people who need sustained support. The examples below illustrate different approaches rather than a single model for adapting to longer lives.
| Example | What is changing | What it addresses |
|---|---|---|
| South Korea | A 2025 pension reform schedules an increase in the mandatory contribution rate from 9% to 13% and raises the future target replacement rate from 40% to 43%. OECD projections say the reform would move the National Pension Fund’s annual deficit from 2041 to 2048 and depletion from 2057 to 2065.[1][2] | Long-term pension financing. The OECD also notes continuing high old-age poverty and recommends further measures, including extending contributions to at least the normal retirement age.[3] |
| China | World Bank-supported projects in Anhui and Guizhou expanded community, home and institutional aged-care services, assessed care needs, trained workers and supported quality standards.[4] | Building service capacity alongside broader priorities to scale up long-term-care insurance and develop a person-centered, three-tier care system.[5] |
| Uzbekistan, North Macedonia and Colombia | Programs described by the World Bank include expanded social-service access and workforce training in Uzbekistan, more licensed social services in North Macedonia, and support for national and local care systems in Colombia.[6][7][8] | Service and institutional development. The cited material does not detail the financing arrangements for long-term care in these three cases.[9] |
The policy implication is that benefits depend on more than pension promises: systems also need workable financing, trained care workers, quality oversight and accessible community-based services. The World Bank describes public stewardship and regulation combined with private-sector service delivery as one general approach; WHO’s May 2026 document is a consultation draft proposing standards, not an enacted national program.[10][11]
Long-term-care insurance: several designs, no standard product
Long-term-care (LTC) insurance helps pay for care when a person meets a policy’s eligibility rules. Private coverage may be sold on its own or bundled with life insurance or an annuity, and benefits may reimburse eligible care expenses or pay a set cash amount.[12]
- Eligibility and waiting periods: Policies can require a specified level of care need and may impose a waiting period before benefits start.[13]
- Limits and covered services: Benefit periods and daily or monthly limits vary. Some policies restrict payment to specified services or eligibility conditions, while cash benefits may offer more flexibility across care types.[14]
- Funding and payment: Public funding, mandatory health insurance, private insurance and personal contributions can coexist. Depending on the arrangement, an insurer may pay providers, reimburse fees or provide a fixed amount.[15][16][17]
- The consumer trade-off: Private cover may add support beyond public provision, but its value depends on eligibility, covered services, waiting periods and benefit limits. The available evidence does not establish a general premium comparison or a universally best-value design.[18][19]
Insurance is only one way to manage the risk of care costs. A related retirement-income trade-off is whether to convert more assets into an annuity that provides income for life or retain accessible savings that could help meet unpredictable care expenses, especially where LTC insurance is unavailable.[20]
Retirement technology: useful projections, important limits
Pension calculators and regular benefit statements can show how contributions, saving duration and investment risk may affect estimated retirement income. Many projections use a single scenario, so they should be read as estimates rather than guarantees.[21][22]
Some tools go further. Chile’s supervisor-created simulator uses stochastic investment-return modelling, including possible crises, to estimate a distribution of pension outcomes using inputs such as mortality tables and annuity rates. The research also describes Chile’s electronic annuity market as a way to reduce information gaps and support competition, but does not evaluate it as a personal planning tool.[23][24][25]
The choice of payout matters: a life annuity provides income for life, while phased withdrawals offer flexibility but do not guarantee income until death. One proposed combination is to use withdrawals earlier in retirement and a deferred annuity for later life.[26][27] However, projections depend on uncertain assumptions such as investment returns, longevity and annuity rates, and can be sensitive to the sequence of returns; complex models may also be costly to design and maintain.[28][29][30]
The research available for this report does not substantiate specific consumer-facing retirement-planning apps or online annuity-comparison platforms. It therefore supports a cautious conclusion: digital projections can help explain choices, but the evidence here does not show that they replace professional advice, guarantee outcomes or provide a complete solution to long-term care financing.
Key takeaways
- Pension reforms can improve projected system finances, but may not by themselves resolve low retirement incomes or poverty, as the South Korea example illustrates.[31][32]
- Public long-term-care programs build services and oversight; insurance can add financial protection, but policy conditions and benefit limits determine how much support a household actually receives.[33][34]
- Retirement technology is most useful when it makes assumptions and uncertainty visible. Income projections and annuity choices need to be considered alongside liquidity for unpredictable care costs.[35][36][37]
Overall, financing longevity is not a choice between government, insurance or fintech. The evidence instead describes complementary roles: public systems organize pensions and care, insurance may transfer part of the care-cost risk, and projections can help people understand retirement-income trade-offs. The main gaps are uneven care-system development, variation in insurance terms, and limited evidence here on specific retirement fintech products.
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
Differential privacy in quantum data sharing
Differential privacy in quantum data sharing
Differential privacy is a way to limit what an analysis reveals about any one person, even when its results are shared. It could help make quantum analyses of sensitive datasets safer to release, but the guarantee depends on how privacy is defined and implemented.
What differential privacy guarantees
A randomized analysis is differentially private when its output would be nearly as likely whether or not one person’s record was included in the dataset. Formally, the probabilities of any possible output differ by at most a multiplicative factor set by ε, plus an optional small additive allowance δ. Smaller ε means stronger protection; δ permits a small probability of additional leakage.[1][2][3]
The practical aim is to make it difficult to infer an individual’s participation from the released result, even if an observer has other information. This protects against a particular kind of inference from outputs; it is not, by itself, a guarantee that all parts of a data-sharing system are secure.[4][5]
Why it matters for quantum analysis
Quantum algorithms may analyze sensitive data, so their outputs can also raise questions about what can be learned about the people represented. Differential privacy can be incorporated at different points, including data preparation and quantum-state encoding, inside a circuit, or at measurement and output. Researchers have also studied whether quantum encoding, subsampling, or compositions of quantum operations can amplify privacy, under particular assumptions.[6][7][8]
One proof-of-concept hybrid approach clipped and noised gradients during the classical optimization of a variational quantum circuit. It reported accuracy alongside privacy protection in simulated classification experiments, but the quantum model was simulated on a classical computer, so it does not establish how well the method works on quantum hardware.[9]
Integration challenges
- There is no unified benchmarking approach: studies differ in how they define neighboring quantum states, measure distance, and introduce randomness.[10]
- Added noise can affect analytical usefulness, so privacy protection must be assessed alongside the utility of the result.[11]
- Researchers call for built-in differential-privacy tools in quantum simulators and cloud platforms, experimental privacy audits, and a dedicated accountant to track cumulative privacy loss across repeated mechanisms.[12][13][14]
- Theoretical privacy amplification results rely on stated assumptions; they do not show that every quantum algorithm or device automatically provides stronger protection.[15]
In short, differential privacy offers a promising way to limit what shared quantum-analysis results reveal about individuals. Practical confidence will require clear privacy definitions, accounting across repeated analyses, and validation of both privacy and usefulness on real systems.[16][17]
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
Why does cyberpunk make the body a political boundary?
In cyberpunk fiction, human-machine interfaces and body-modifying technologies bring questions of control and identity sharply into focus by erasing the boundaries between biology and digital systems. Technologies ranging from direct neural links to cybernetic prosthetics demonstrate how the human body can function as a site of corporate power, economic coercion, and systemic pressure rather than just personal expression or futuristic decoration.
When digital integration becomes a baseline requirement for daily functioning, accessing a home, attending school, or completing financial transactions, bodily modifications cease to be optional enhancements and instead become mandatory tools for economic survival[1]. For instance, in the Cyberpunk universe, workers and marginalized individuals face immense pressure to adopt specialized cybernetic tools or neural augmentations simply to maintain employment or secure housing[2]. This dynamic turns physical alteration into a political boundary where individuals are disciplined by technological dependencies, corporate surveillance, and unequal access to capital. Rather than offering straightforward liberation, modifying the body often exposes individuals to deep vulnerabilities, institutional control, and the risk of losing agency over their own minds and actions[3].
Would you also like to know how corporations in cyberpunk media exert control through virtual environments?Réponse terminée. Une option de suivi est disponible.
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
The terrier and the ducklings
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
A Little Ride Above the Sea
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
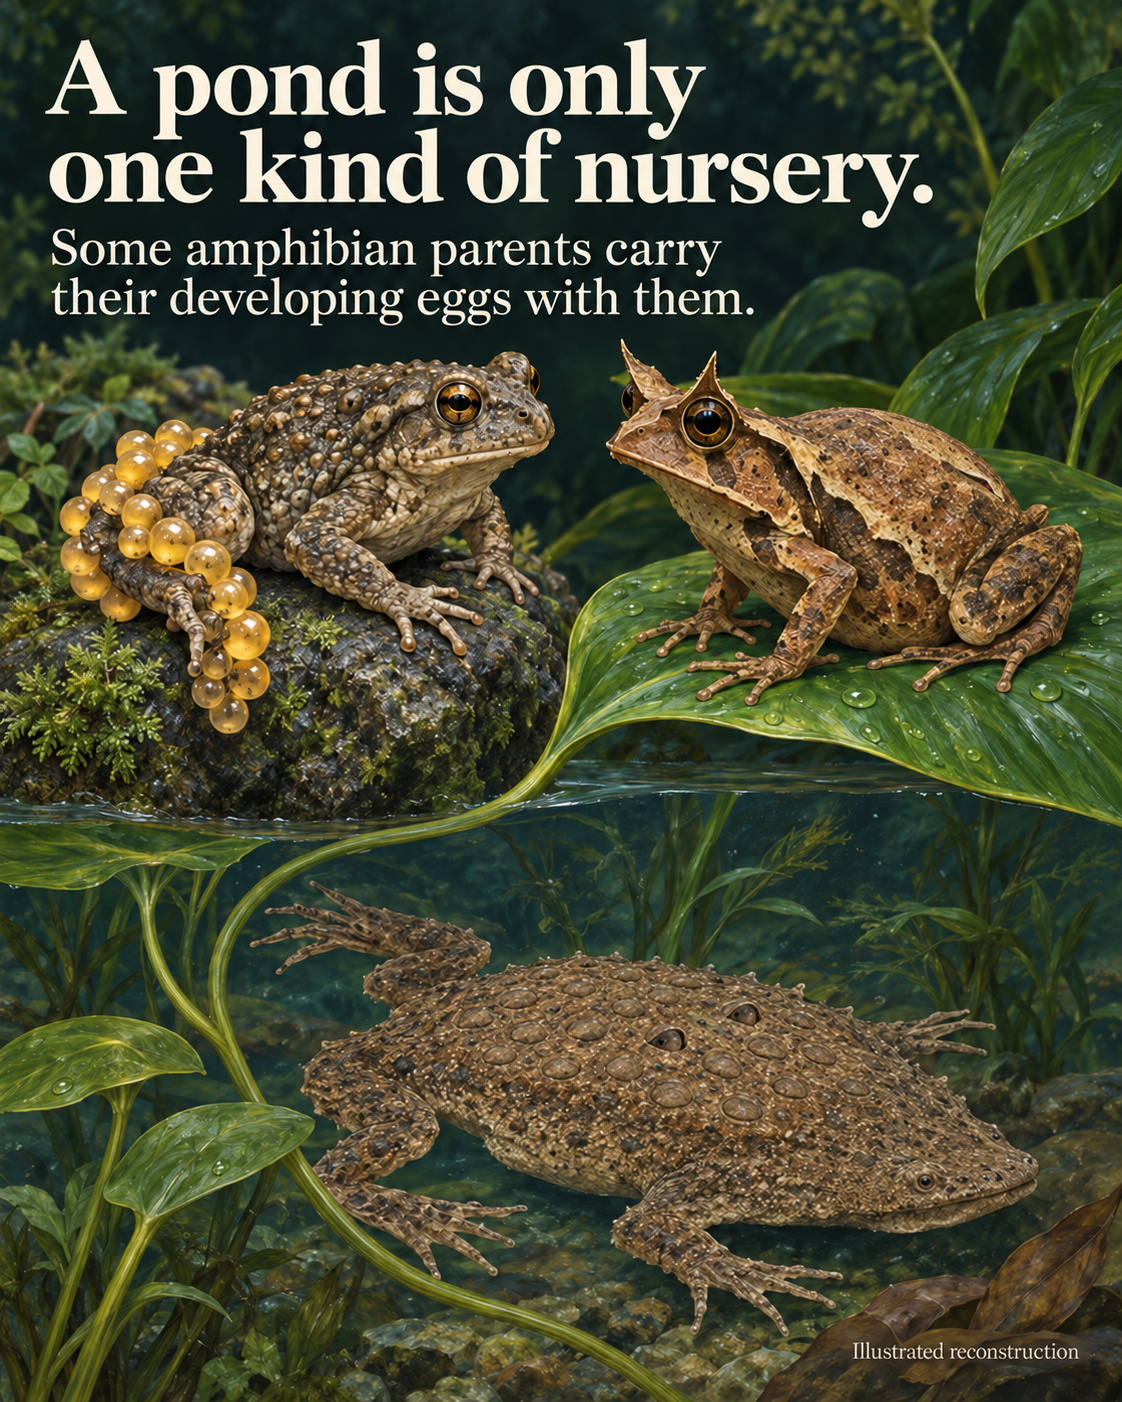
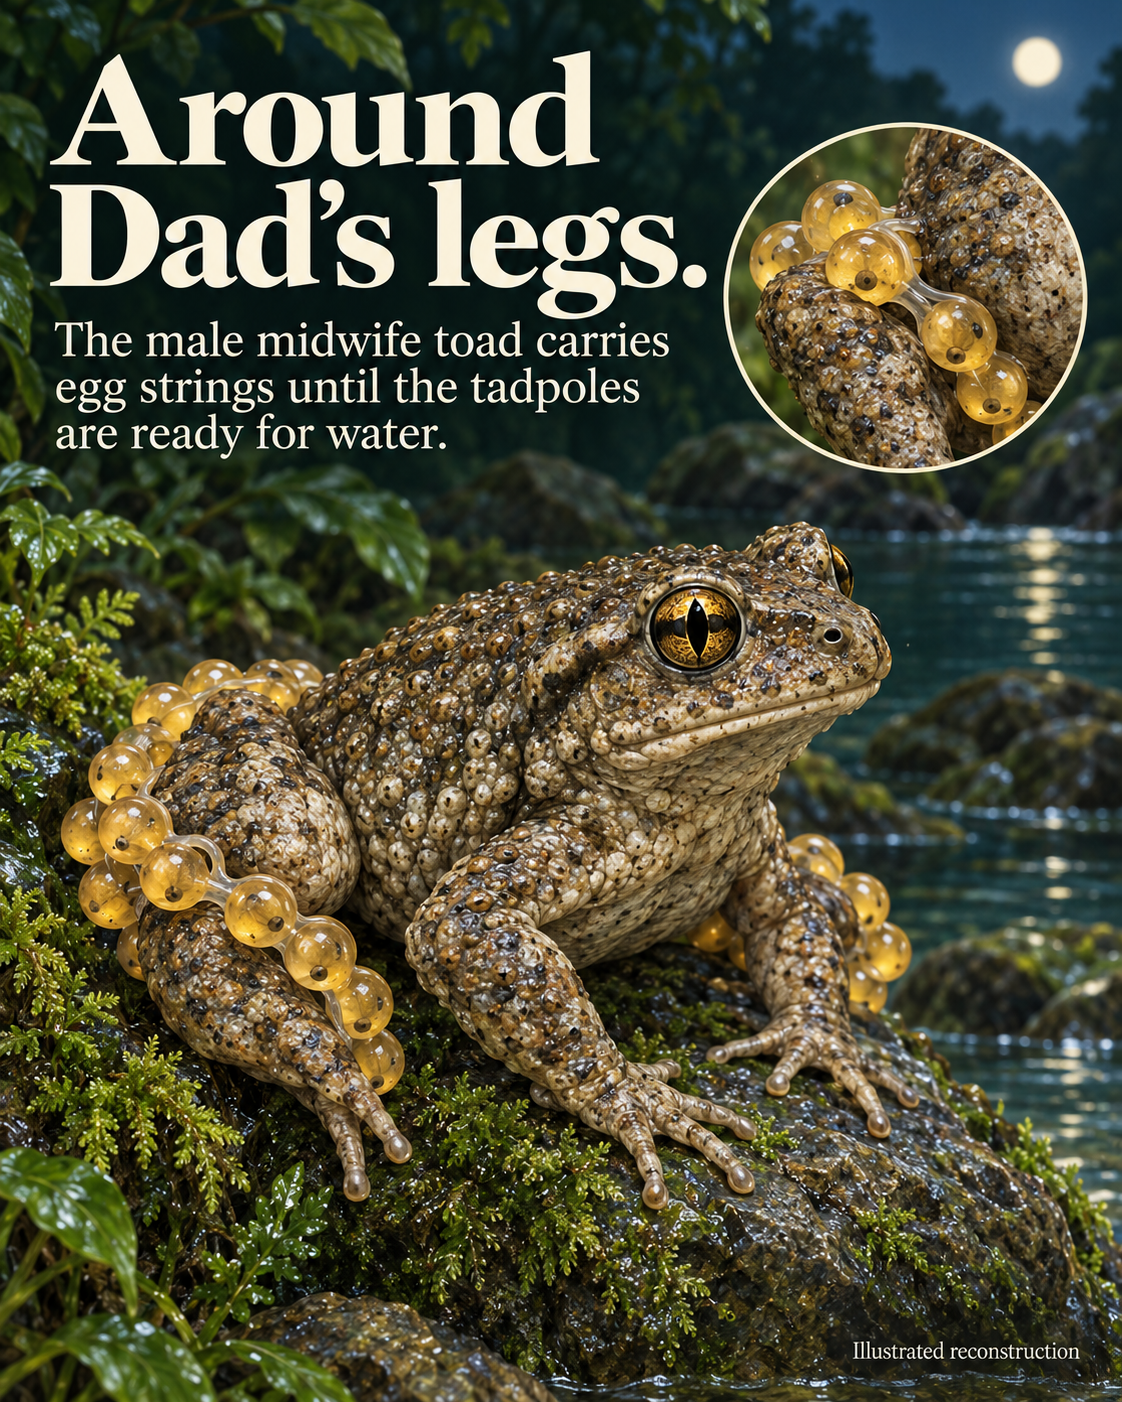
Three places frogs carry their eggs
 1/5
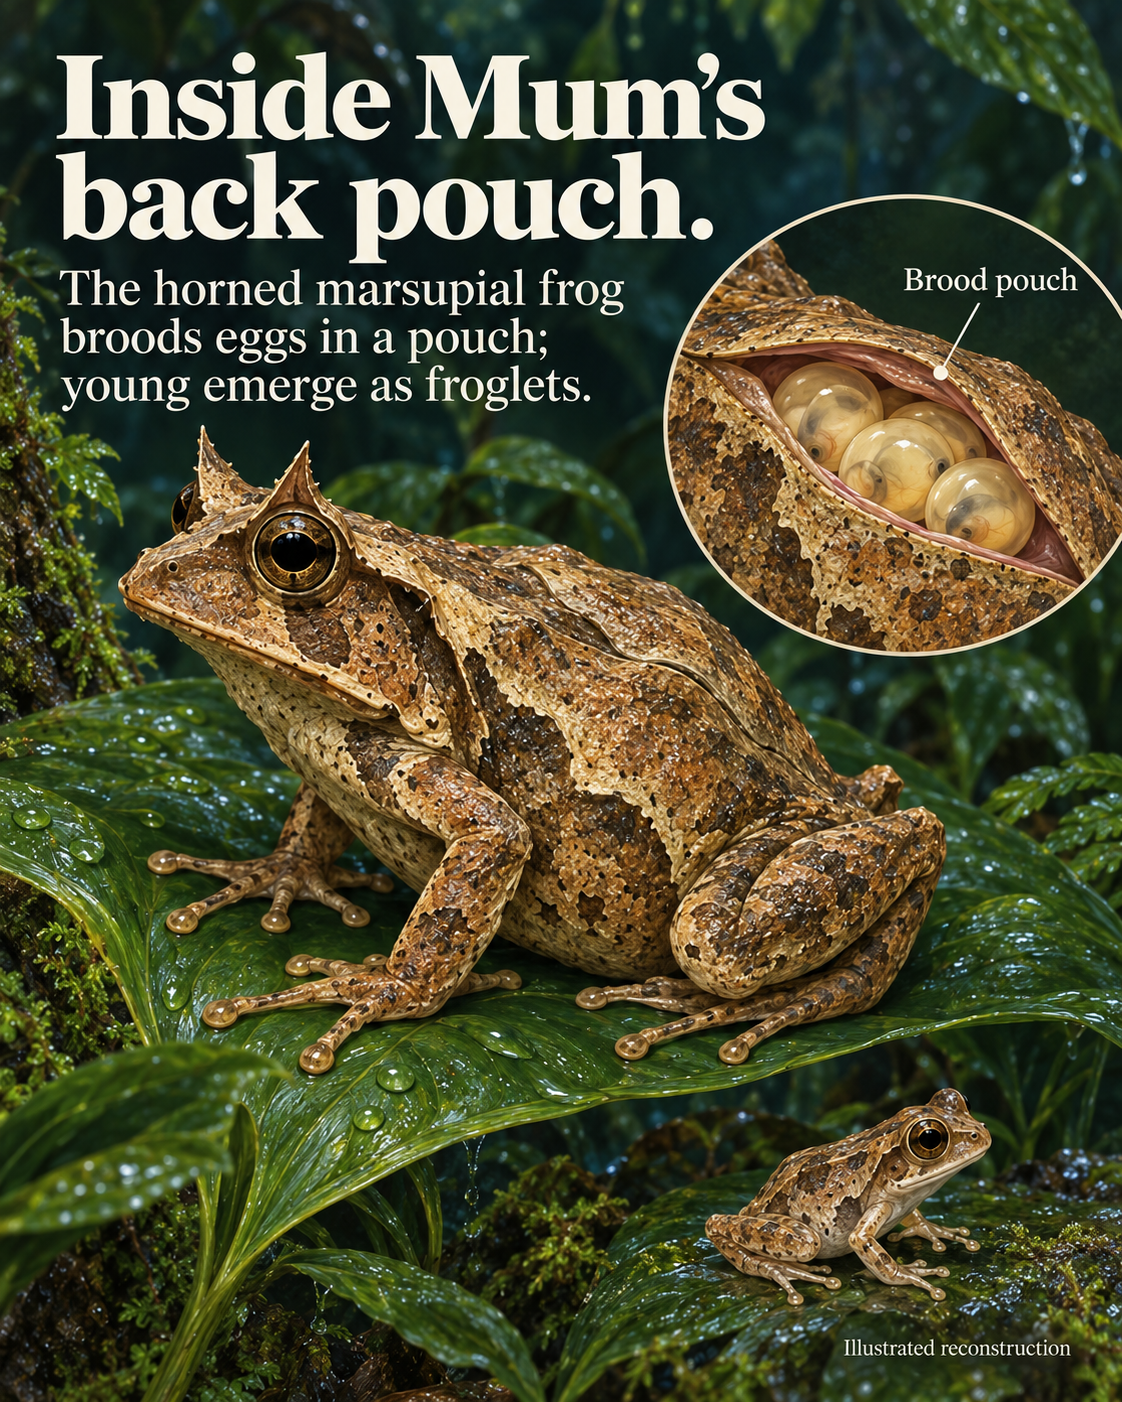
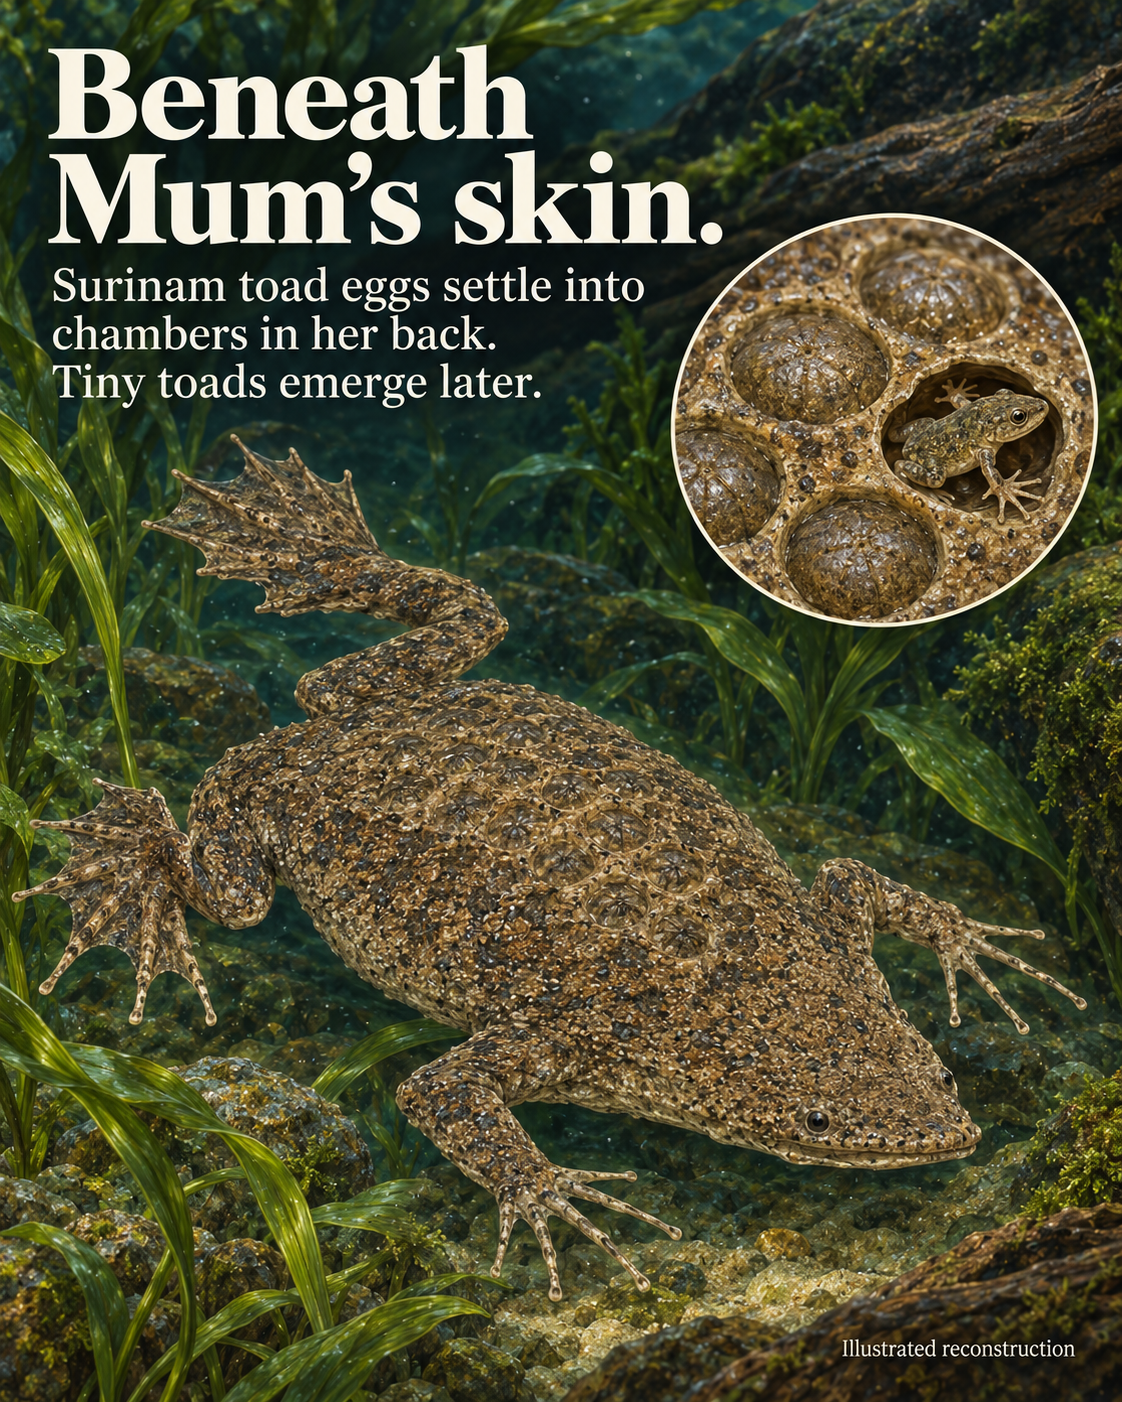
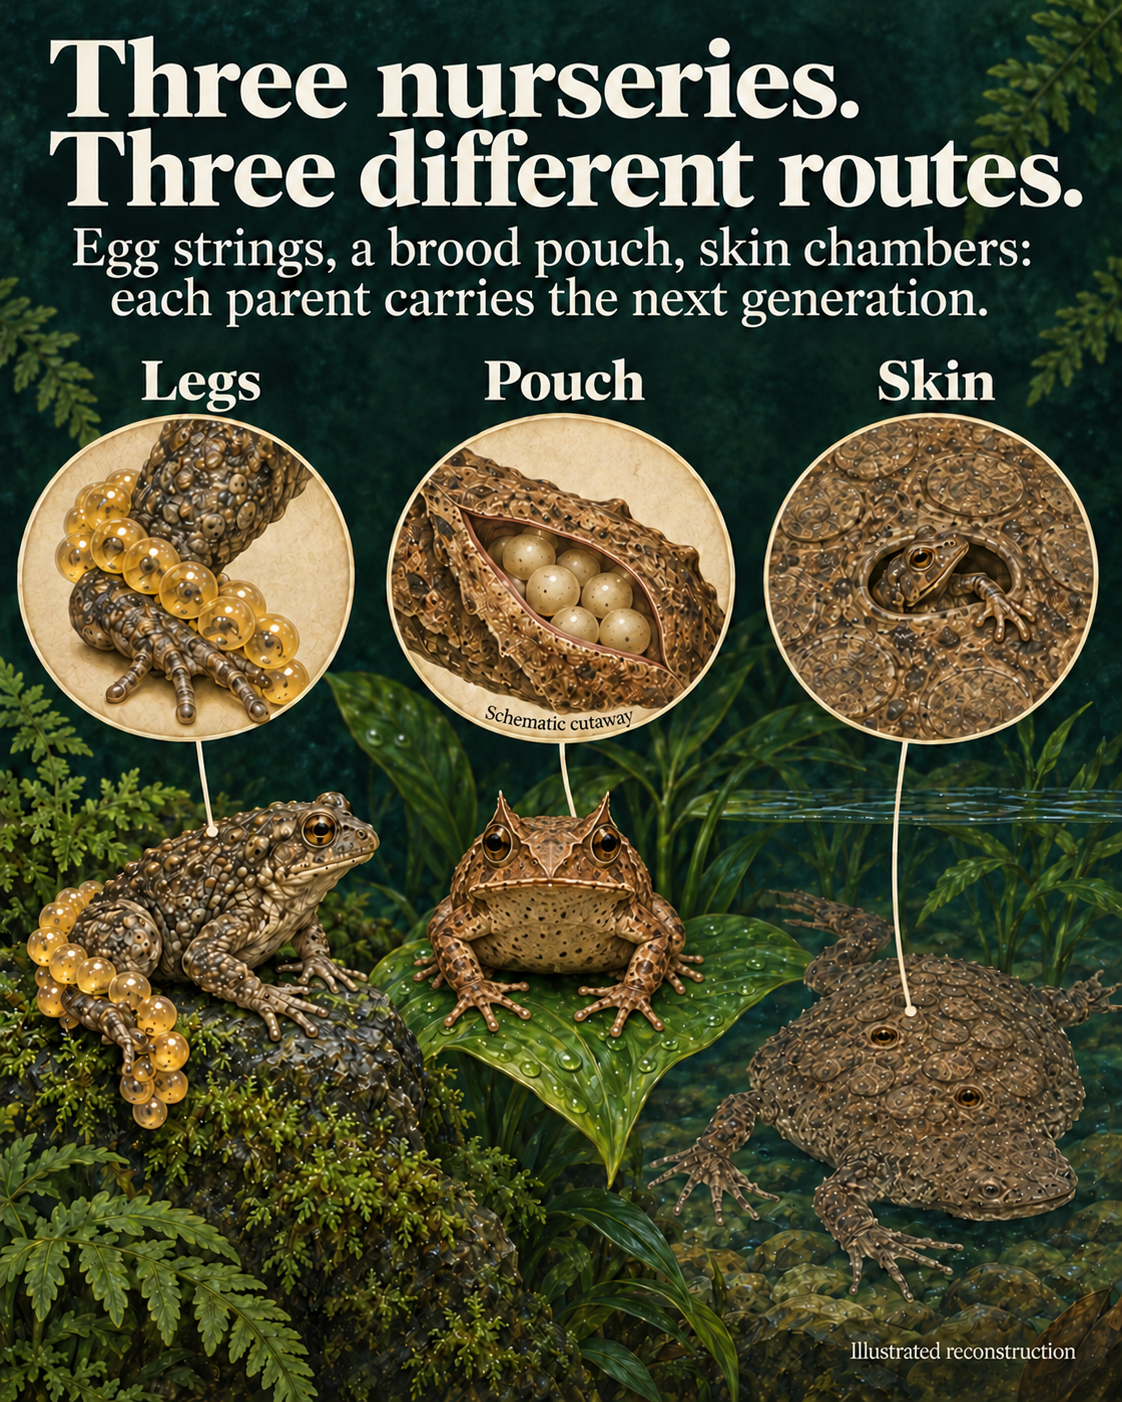
Lire le texte des diapositives
- A pond is only one kind of nursery.
Some amphibian parents carry their developing eggs with them.
- Around Dad’s legs.
The male midwife toad carries egg strings until the tadpoles are ready for water.
- Inside Mum’s back pouch.
The horned marsupial frog broods eggs in a pouch; young emerge as froglets.
- Beneath Mum’s skin.
Surinam toad eggs settle into chambers in her back. Tiny toads emerge later.
- Three nurseries. Three different routes.
Egg strings, a brood pouch, skin chambers: each parent carries the next generation.
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
How far could an earthquake move the ground?
Loudon describes the Calabrian earthquakes as cracking the ground and lowering or levelling hills. She names Sir William Hamilton as an authority who gave a detailed account of the earthquakes[1][2].
One reported scene makes the scale vivid: a piece of ground a mile long and half a mile wide, carrying two cottages and several trees, was said to have travelled about a mile down a valley, with the houses and most trees still upright. That is what Loudon’s historical account claims, not a movement independently verified here as a present-day fact[3].
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
Two lights above. Another below.
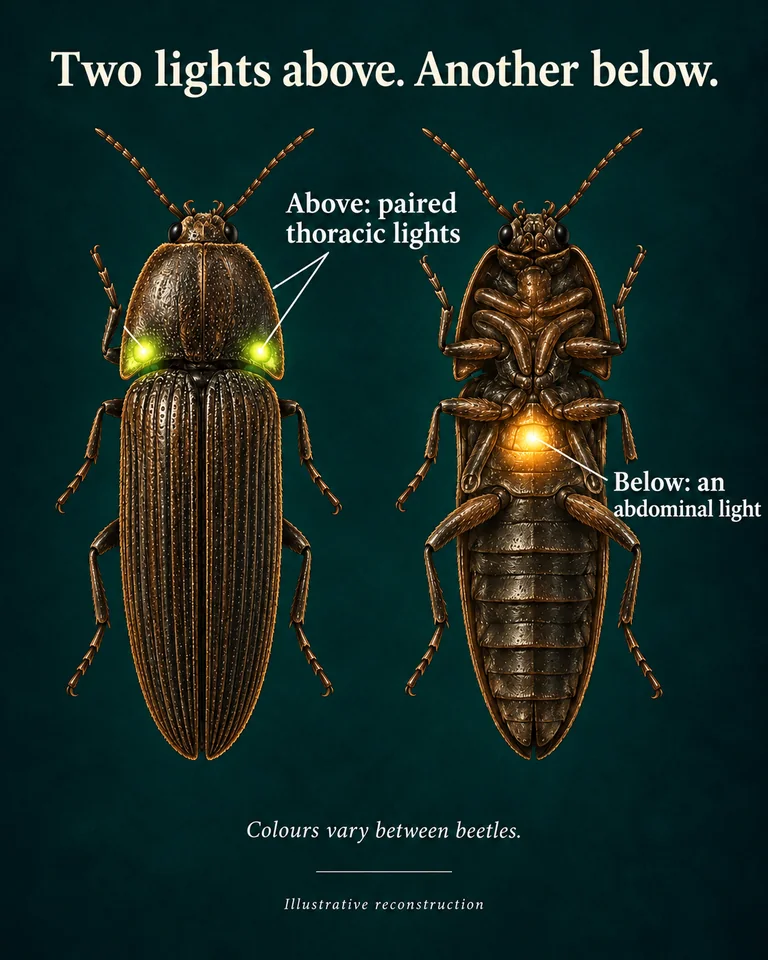
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).
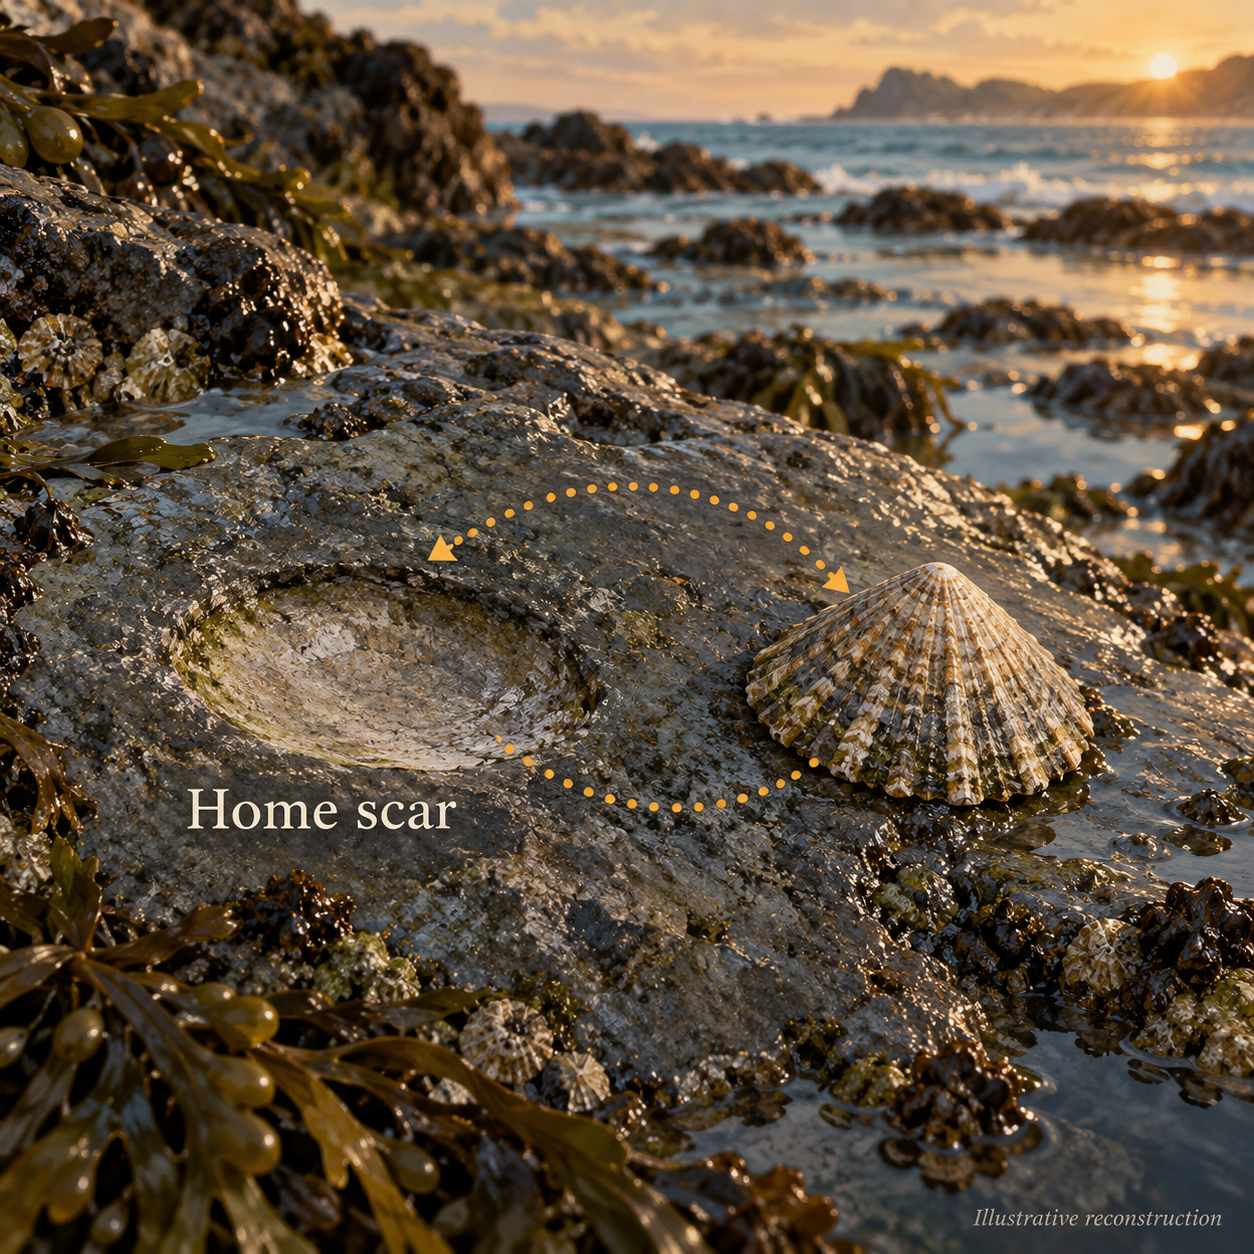
This limpet has a home address
This limpet has a home address. A common limpet can leave its resting spot to graze, then return to the same shell-shaped patch of rock: its “home scar.” That little cap on the shore may have a familiar place to come back to.
Examinons les alternatives :
- Modifier la requête.
- Démarrer une nouvelle conversation.
- Supprimer des sources (si elles ont été ajoutées manuellement).